Home loan EMI calculator is a simple way to estimate how much you may need to pay every month on a home loan. If you’re planning to borrow ₹30 lakh, ₹50 lakh, or even ₹1 crore, checking the EMI before applying can help you understand whether the repayment fits your budget.
But the monthly EMI is only one part of the picture. The interest rate, loan tenure, down payment, and total interest can make a big difference to the overall cost of your loan.
In this guide, we’ll explain how home loan EMI is calculated in India, show a real ₹50 lakh example, and explain the factors that can change your monthly payment. You can also use our free EMI Calculator to compare different loan amounts and repayment periods.
What Is EMI?
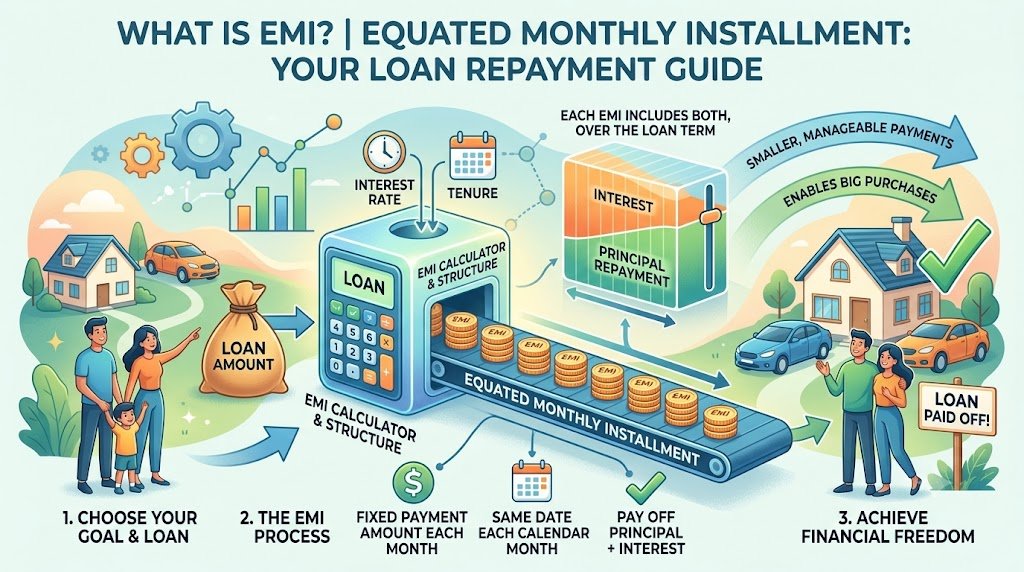
EMI (Equated Monthly Instalment) is the fixed monthly payment a borrower makes toward a loan over a specified repayment period.
For a typical home loan, each EMI contains two parts: principal repayment and interest. The proportion going toward each part changes during the loan period.
For example, if you borrow ₹50 lakh for 20 years, your monthly EMI depends mainly on the loan amount, interest rate, and tenure.
If you’re also comparing ways to invest your money, you may find our guide on SIP vs lumpsum investing useful.
Home Loan EMI Calculation Formula
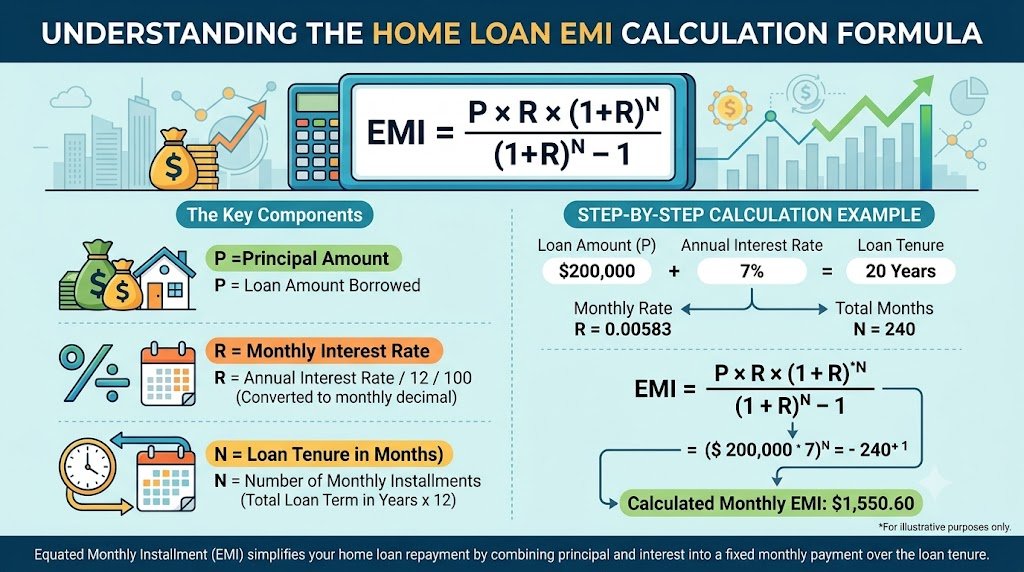
The standard EMI formula is:
EMI = P × R × (1 + R)ⁿ / [(1 + R)ⁿ − 1]
Where:
- P = Principal loan amount
- R = Monthly interest rate
- N = Total number of monthly instalments
The annual interest rate needs to be converted into a monthly rate before using the formula.
Before comparing different loans, you can use a home loan EMI calculator to check how the interest rate and tenure affect your monthly payment.
Example: ₹50 Lakh Home Loan
Suppose you take:
| Loan detail | Example |
|---|---|
| Loan amount | ₹50,00,000 |
| Annual interest rate | 8.5% |
| Loan tenure | 20 years |
| Number of EMIs | 240 |
The monthly interest rate is:
8.5% ÷ 12 = 0.7083% per month
Converted into decimal form:
0.085 ÷ 12 = 0.007083
Using the EMI formula, the monthly EMI works out to roughly ₹43,391.
Over 240 months, the total amount paid would be about ₹1.04 crore, including roughly ₹54.14 lakh in interest.
A home loan EMI calculator makes this comparison easier because you can test 15-year, 20-year, and 25-year repayment periods within seconds.
For quick calculations, you can enter these numbers into the Sahitool EMI Calculator instead of calculating the formula manually.
Factors That Affect Home Loan EMI
Your EMI isn’t determined by the loan amount alone. Several factors can change your monthly payment and total interest.
1. Loan Amount
The bigger the loan, the higher the EMI, assuming the interest rate and tenure remain the same.
For example, borrowing ₹40 lakh instead of ₹50 lakh can reduce your monthly repayment considerably. This is one reason a larger down payment may reduce the borrowing burden.
But don’t empty your savings just to reduce the loan. You still need money for registration, interiors, emergencies, and other expenses.
2. Interest Rate
The interest rate has a direct effect on both your EMI and total interest cost.
Consider a ₹50 lakh loan for 20 years:
| Interest rate | Approx. monthly EMI |
|---|---|
| 7.5% | ₹40,280 |
| 8.5% | ₹43,391 |
| 9.5% | ₹46,607 |
Even a one-percentage-point difference can make a noticeable difference over a long repayment period.
For current information on lending rates and monetary policy, borrowers can refer to the Reserve Bank of India (external link — opens in a new tab; use rel="noopener" when adding the link in WordPress).
3. Loan Tenure
Loan tenure is the length of time you take to repay the loan.
A longer tenure generally reduces the monthly EMI, but you’ll usually pay interest for more months.
For example, a ₹50 lakh loan at 8.5% could look approximately like this:
| Tenure | Approx. EMI | Approx. total interest |
|---|---|---|
| 15 years | ₹49,237 | ₹38.63 lakh |
| 20 years | ₹43,391 | ₹54.14 lakh |
| 25 years | ₹40,261 | ₹70.78 lakh |
The numbers show why looking only at the EMI can be misleading. A lower monthly payment doesn’t automatically mean a cheaper loan.
4. Down Payment
Your down payment is the amount you pay from your own funds before taking the loan.
Suppose a property costs ₹60 lakh.
- ₹10 lakh down payment → ₹50 lakh loan
- ₹15 lakh down payment → ₹45 lakh loan
- ₹20 lakh down payment → ₹40 lakh loan
A larger down payment means a smaller principal, which can reduce both EMI and total interest.
However, keep enough cash aside for other property-related costs and emergencies.
5. Type of Interest Rate
Home loans may have different interest-rate structures, such as floating or fixed-rate arrangements depending on the lender and loan product.
With a floating-rate loan, the applicable rate can change according to the loan’s terms and benchmark-related changes. That can affect your repayment schedule.
Before accepting an offer, read the lender’s loan documents carefully rather than relying only on the advertised interest rate.
Home Loan EMI Calculator: How It Works
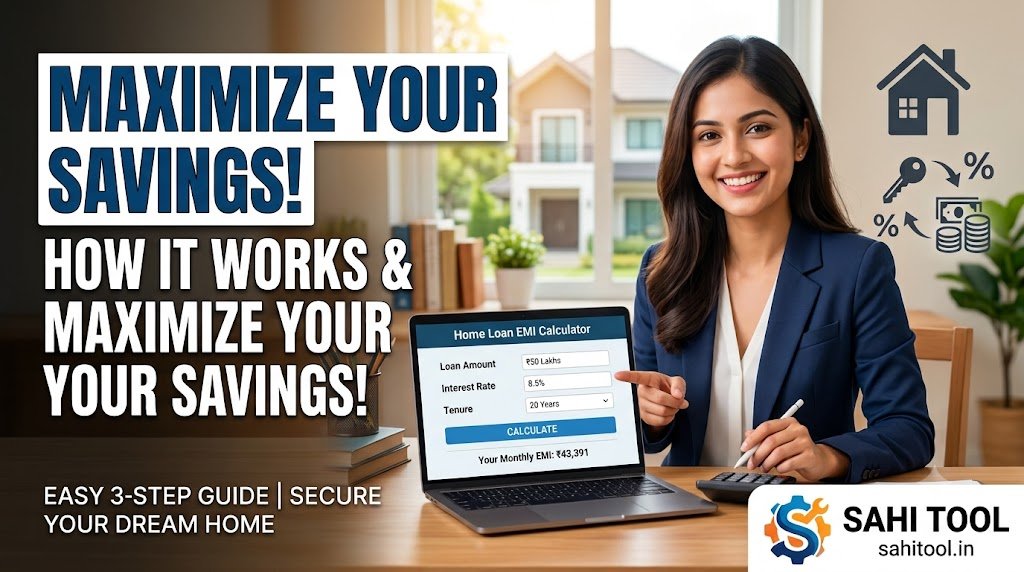
Our home loan EMI calculator lets you estimate your monthly repayment by entering the loan amount, interest rate, and tenure.
Here’s how to use the Sahitool EMI Calculator:
- Enter the loan amount — for example, ₹50,00,000.
- Enter the annual interest rate — such as 8.5%.
- Enter the loan tenure — such as 20 years.
- Check the estimated monthly EMI.
- Compare different combinations of loan amount, rate, and tenure.
- Look at the total interest payable, not just the monthly EMI.
Here’s a useful approach: calculate the EMI for a 15-year, 20-year, and 25-year tenure. The comparison can make the cost difference much easier to understand.
Common Mistakes to Avoid
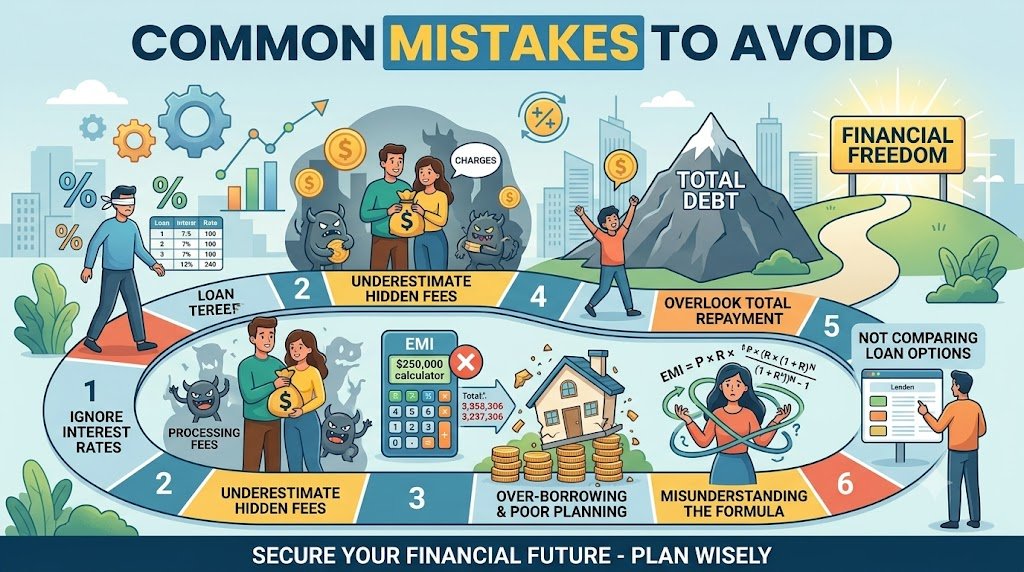
1. Looking Only at the Monthly EMI
A ₹40,000 EMI may look comfortable, but you also need to consider the total amount you’ll repay over the entire loan period.
Always check principal + total interest, not just the monthly figure.
2. Choosing the Longest Tenure Automatically
A longer tenure can make the EMI easier to manage, but it may increase your overall interest cost substantially.
Choose a tenure that fits your cash flow rather than simply selecting the lowest EMI.
3. Ignoring Additional Loan Costs
Your borrowing cost may include charges beyond interest, depending on the lender and loan.
Check the lender’s documentation for applicable processing fees, legal or technical charges, insurance requirements, and other costs.
4. Assuming the Interest Rate Will Never Change
If your loan has a floating interest rate, changes can affect your repayment schedule.
Ask the lender what happens to your EMI or tenure when the applicable rate changes.
5. Taking the Maximum Loan You Qualify For
Being eligible for a particular loan amount doesn’t necessarily mean you need to borrow that much.
Your monthly budget should leave room for household expenses, emergencies, investments, and other financial commitments.
Frequently Asked Questions
Is a Home Loan EMI Calculator Accurate?
An EMI calculator is accurate for the numbers you enter and the mathematical EMI formula used. However, the actual amount charged by a lender can differ because of the loan’s specific terms, rate changes, fees, insurance, or other applicable charges. Treat the calculator’s result as an estimate and verify the final repayment schedule with your lender.
How Is Home Loan EMI Calculated in India?
Home loan EMI is generally calculated using the principal amount, applicable interest rate, and number of monthly instalments. The standard formula uses the monthly interest rate and total number of payments. You can use an EMI calculator to avoid doing the calculation manually.
Can I Reduce My Home Loan EMI?
You may be able to reduce your EMI by borrowing a smaller amount, negotiating a lower applicable interest rate where possible, or choosing a longer repayment tenure. However, extending the tenure can increase total interest paid. Some borrowers may also consider part-prepayment, subject to their loan terms and applicable charges.
Does a Higher Down Payment Reduce EMI?
Yes. A higher down payment means you borrow less money, assuming the property price remains unchanged. For example, borrowing ₹40 lakh instead of ₹50 lakh generally results in a lower EMI when the interest rate and tenure are the same. You should still maintain an adequate emergency fund rather than putting every available rupee into the down payment.
Can Home Loan Interest Rates Change?
That depends on the type and terms of your loan. Floating-rate loans can change when the applicable benchmark or lending rate changes, while fixed-rate arrangements have different conditions. The Reserve Bank of India provides information on India’s monetary and banking framework (external link — opens in a new tab; use rel="noopener" when adding the link in WordPress).
Can I Prepay My Home Loan?
Depending on the loan type and lender terms, borrowers may be able to make partial or full prepayments. The effect can be different depending on whether you reduce the EMI, shorten the tenure, or make another adjustment. Before prepaying, check your lender’s current terms and charges.
For broader personal-finance information, you can also review the Income Tax Department’s official portal (external link — opens in a new tab; use rel="noopener" when adding the link in WordPress) for current tax-related information rather than relying on outdated articles.
Final Thoughts
A home loan EMI calculator is useful for getting a quick estimate, but your actual borrowing decision should also consider the total interest and your monthly budget.
If you’re comparing different loan options, try a few combinations in the free Sahitool EMI Calculator and compare the total cost as well as the monthly payment.
A few minutes of calculation now can make a long-term loan much easier to understand.
Disclaimer
This article is for informational purposes only and does not constitute financial advice. Loan rates, terms, fees, and eligibility criteria vary between lenders and can change over time. Check the latest terms with the relevant lender and consult a qualified financial professional if you need personalized advice.